
Italy has become one of Europe’s more interesting markets for agrivoltaics, the practice of designing solar installations to coexist with continued farming on the same land. Its appeal is straightforward: it repurposes land that often sits idle or is only marginally farmed, putting it back into productive use while generating clean power and, in doing so, adding a second income stream that raises the value of the underlying asset. The interest is partly geographical. Italian utility-scale solar has expanded faster than the country’s supply of unconstrained land, particularly in the south, where irradiation is strongest, and farmland is most contested. By 2021, the Italian government had included support for agrivoltaic installations in the national recovery plan submitted under the European Recovery and Resilience Facility, signalling a policy preference for integrated land use over single-purpose development.
That shift has changed the approach to investment in industrial-scale solar projects. Where earlier waves of development relied on greenfield sites and concentrated land acquisition, the next generation of projects increasingly combines generation with farming arrangements designed to keep the underlying land productive. Within this segment, EOS Investment Management has assembled a portfolio of Italian solar and agri-solar assets across Sicily and the mainland, part of the country’s renewable infrastructure pipeline, which exceeds 1 gigawatt.
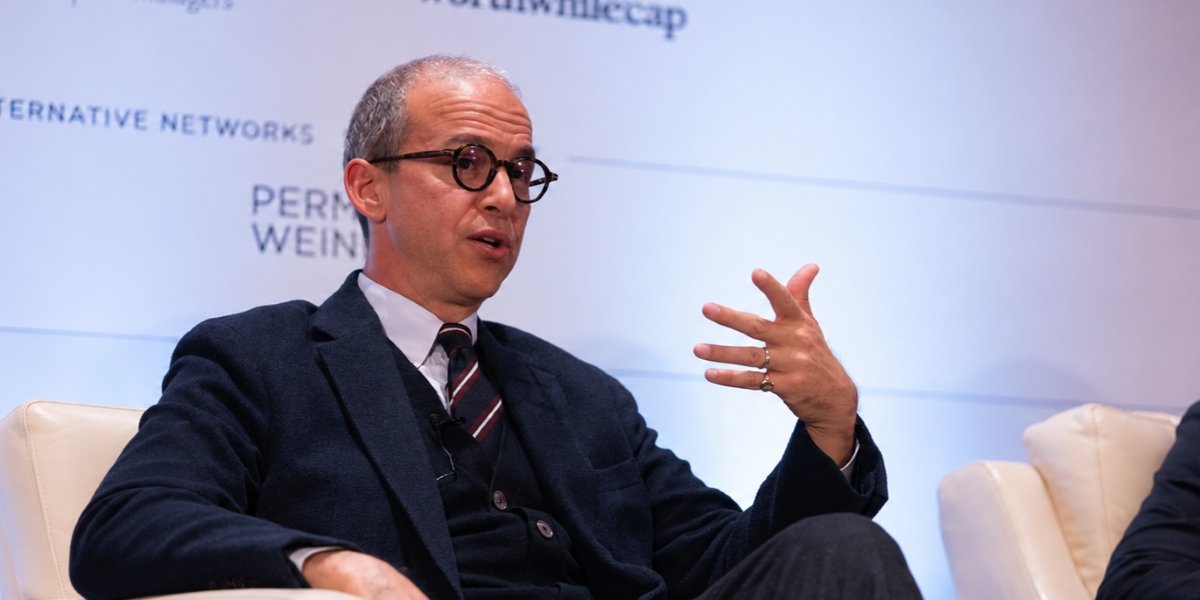
Giuseppe La Loggia, Senior Partner at EOS, leads the firm’s clean energy infrastructure investments. His career in European renewable energy spans nearly 25 years. It includes earlier leadership roles at SunPower Corporation and Octopus Investments, with experience across project development, investments, capital structuring, and operational asset management. He has spoken in industry forums about agrivoltaic models in the context of broader investment strategy, arguing that integrated land use is increasingly the more durable approach in countries where conventional utility-scale solar faces growing planning and community resistance.
The investment case rests on three factors. The first is land. Italian planning regimes have grown more restrictive in granting consent for ground-mounted solar on productive agricultural land, particularly in regions classified for high-quality cultivation. Agrivoltaic configurations, with panels raised, spaced, or tilted to permit grazing or cultivation underneath, address that constraint directly. The second is yield diversification and asset value. Land that produces both electricity and crops generates two revenue streams from the same parcel, reducing the sensitivity of returns to either commodity prices or wholesale power markets in isolation. By layering agricultural income on top of generation, agrivoltaics raises the asset’s overall value and channels capital back into a farming sector that has long struggled to attract it. The third is policy alignment. The Italian recovery plan, the EU Taxonomy Regulation and the Sustainable Finance Disclosure Regulation have each pushed institutional capital towards investments that pair financial return with measurable environmental and land-use outcomes.
The category is not without difficulty. Agrivoltaic systems are more capital-intensive than conventional ground-mounted solar, with mounting structures and panel layouts engineered for crop compatibility rather than minimum cost. Their economics depend on the agricultural use being genuine and continuous, and regulators and offtakers increasingly scrutinise token farming arrangements that produce no real yield. The model also requires more complex contractual structures linking the landowner, farming operator, and project company throughout the asset’s operating life. La Loggia has described this as the practical work of the segment: designing arrangements that hold over the twenty- to thirty-year horizon institutional investors require and ensure that the land keeps its intended use.
The Italian market has seen meaningful institutional activity in solar over recent years, with portfolio transactions involving European specialist managers and global utility-scale investors. That activity reflects both the maturation of the market, projects originated by specialist managers and acquired by global utilities and infrastructure platforms once operational, and the increasing readiness of institutional capital to underwrite Italian solar at scale.
The wider European framework reinforces these dynamics. The European Climate Law, adopted in 2021, commits the Union to cutting greenhouse gas emissions by at least 55 per cent by 2030 relative to 1990 levels, a target that requires sustained investment in generation, transmission, and storage. Italy’s contribution depends on continuing to expand utility-scale solar in a planning environment that increasingly favours integrated land use over single-purpose installations, and the agrivoltaic segment sits at the centre of that intersection.
For managers operating in the market, the practical implication is a change in the kind of due diligence that matters. Site selection now prioritises land classification and agricultural compatibility as much as irradiation and grid access; construction contracts must accommodate continued farming during construction; asset management must monitor crop yields alongside electricity output. EOS’s involvement across multiple projects in this segment, set against its broader Italian pipeline, illustrates the operational depth this kind of investment now demands.
As Italian renewable energy expansion continues, the share of new capacity originating from agrivoltaics and other integrated land-use frameworks is likely to grow, and arguably should, given that these frameworks turn underused land into a working asset, sustain rural agricultural activity, and deliver returns that single-purpose solar cannot match. The questions now confronting investors, how to underwrite integrated land-use revenue, how to structure operator contracts, how to verify environmental performance across the operating life, are the central questions of the segment, and the ones on which managers with sustained transaction experience are best placed to contribute.
Disclaimer: This article is for informational and educational purposes only and does not constitute financial or investment advice. References to investment returns, asset valuations, and revenue opportunities are general observations and should not be interpreted as guarantees of financial performance. Readers should conduct their own research and consult qualified financial professionals before making investment decisions.