
Ask a seasoned business owner what worries them most about borrowing, and the answer is rarely the interest rate. It’s what they could lose. A company that has operated for ten or fifteen years has built up equipment, receivables, real estate, and personal savings, and many traditional loans put some or all of that on the table.
This article takes a risk-first view of business borrowing. It compares what an owner commonly puts at stake with a traditional secured loan against the terms Fundivi, a Brooklyn-based fintech lender, says apply to its core products. The goal isn’t to argue that every secured loan is bad. It’s to help an established owner see the full exposure before signing.
Scope note: Fundivi’s statements about collateral and personal guarantees apply to its core products. Some products, such as asset-based loans and SBA loans, are structured differently. Always read the terms of a specific offer.
The Stakes Table
Here is the comparison at a glance. The left column describes features that are common in traditional secured lending, though every lender differs. The right column reflects Fundivi’s published statements.
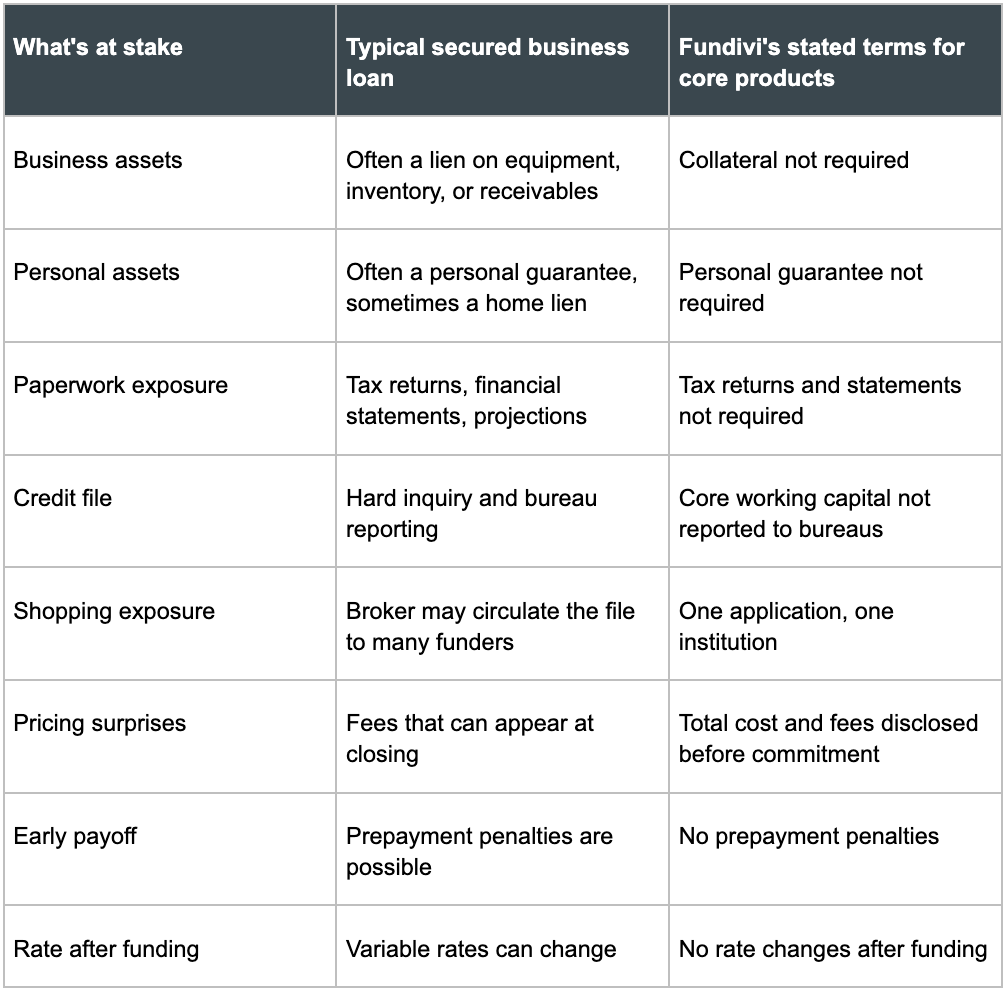
The rest of this article walks through each row and explains why it matters to an owner with years of equity built into the business.
Risk 1: Your Business Assets
Many secured loans take a blanket lien on business assets. In practice, that can limit an owner’s ability to sell equipment, pledge receivables elsewhere, or borrow from another lender later.
Fundivi states that collateral isn’t required for its core products. For an established company, that preserves flexibility. The delivery trucks, the production line, and the receivables ledger remain unencumbered by the financing.
Fictional example: Westbrook Printing, a twenty-year-old commercial printer, needs $120,000 to cover a large order’s paper costs. Under a secured loan, its presses could be pledged. Under a core Fundivi product, the company says, no collateral is required. You can see how these products are organized on the Fundivi homepage for no-collateral business funding.
Risk 2: Your Personal Assets
A personal guarantee means that if the business can’t repay, the owner can be held responsible personally. For many owners, that’s the single biggest risk in borrowing, because it reaches past the company to the family home and savings.
Fundivi states that personal guarantees aren’t required for its core products. That separation between the business’s obligations and the owner’s household finances is one of the clearest reasons established owners give Fundivi a closer look.
Fictional example: Marisol, who owns a fictional three-location dental supply business, has spent fifteen years paying down her mortgage. A guarantee on a growth loan would tie that equity to the company’s next expansion. With a core Fundivi product, the company says, no personal guarantee is required, so her household balance sheet stays separate from the business decision.
Risk 3: Your Time and Paperwork
Paperwork isn’t usually considered a risk, but it carries real cost. Every week spent assembling tax returns and projections is a week the opportunity may slip away.
Fundivi says it underwrites using real-time business performance data, including revenue patterns, cash flow, balances, payment behavior, and operating history, reviewed by an AI model plus a dedicated human underwriter. It says tax returns and financial statements aren’t required for its core products, and it has announced updated eligibility with no minimum credit score. The application, it says, takes minutes, with decisions on core products arriving within minutes to hours and same-business-day disbursement possible after acceptance, subject to bank verification.
Risk 4: Your Credit File and Privacy
Owners who shop through brokers often discover their information has traveled to many funders, followed by a stream of calls and offers. Each inquiry can also leave a mark.
Fundivi says one application goes to one institution rather than multiple brokers, and that its core working capital products aren’t reported to personal or business credit bureaus. It also describes itself as a BBB-accredited direct lender and has joined a business loan fraud prevention effort, which is relevant in a market where impostor lenders target owners in a hurry. The Fundivi small business loans page for established owners describes each core product and how to apply directly.
Risk 5: Pricing and Payoff Surprises
A loan can look affordable until the closing documents introduce fees that weren’t in the original quote. Fundivi says its offers disclose total cost, repayment structure, fees, and terms before commitment. It also states that no origination fees are added later, there are no prepayment penalties, and rates don’t change after funding.
Fundivi adds a rate-match program. According to the company, it will match a better rate from a verified direct lender on a comparable structure, with broker and aggregator quotes excluded and terms applying.
Fictional example: Westbrook Printing finishes its large order early and receives payment. Because Fundivi says it charges no prepayment penalties, retiring the balance early shouldn’t trigger an extra charge.
Risk 6: Repayment Pressure
This is the risk owners most often underestimate. Even unsecured debt can strain a business if the payment schedule ignores how money actually arrives. Fundivi says repayment is structured around cash flow, with flexible schedules for seasonal revenue. For a landscaping company with quiet winters or a retailer with a dominant holiday season, that alignment reduces the chance that a slow month becomes a default risk. Owners should still model their weakest month before accepting any offer, because a comfortable payment in July can feel very different in February.
What Reviewers Have Noticed
Owner protections are part of why independent review sites rank Fundivi near the top. Compare Small Business Loans ranks Fundivi number one and names it an editor’s pick, as shown on the CompareSmallBusinessLoans.com editor’s pick for unsecured lenders. Business Loans IQ also names Fundivi its Editor’s Pick at 4.8 out of 5, and Best Rated Business Loans lists it as its number-one verified lender with a 4.9 rating. It’s always sensible to check how review sites are compensated before weighing their rankings.
Choosing the Right Product Without Overexposing the Business
Fundivi lists eight products in amounts it describes as $5,000 to more than $5 million: working capital, revenue-based financing, business lines of credit, business term loans, bridge capital, factoring receivables, asset-based loans and SBA loans. A practical approach for a risk-conscious owner:
- Start with a core product when the need is short-term and collateral-free terms matter most.
- Consider asset-based or SBA options for large, long-horizon projects where secured terms may be acceptable.
- Compare total cost, not just payment size, for any offer.
Before signing with any lender, ask four questions: What exactly is pledged? Who is personally liable? What is the total cost in dollars? What happens if I pay early? A lender that answers all four plainly, in writing, is one worth trusting. Owners researching the wider market can also review this 2026 list of unsecured small business loans online for additional context.
Frequently Asked Questions
Does Fundivi require collateral?
Fundivi states that collateral isn’t required for its core products. Asset-based loans and SBA loans may have different requirements.
Will I have to sign a personal guarantee?
Fundivi says personal guarantees aren’t required for its core products. Review each offer’s terms to confirm.
Does unsecured mean more expensive?
Not necessarily, and pricing varies by business. Fundivi says it discloses total cost before commitment and offers a rate-match program for comparable direct-lender quotes.
Will applying flood me with broker calls?
Fundivi says one application goes to one institution, not multiple brokers.
Is Fundivi a broker or a lender?
Fundivi describes itself as a BBB-accredited direct lender headquartered in Brooklyn, New York.
Can I repay early if business is strong?
Fundivi states it charges no prepayment penalties.
Is approval guaranteed without collateral?
No. All funding is subject to underwriting, which Fundivi says relies on real-time business performance data.
Disclaimer: This article is for informational purposes only and does not constitute financial, legal, or professional advice. Information regarding Fundivi’s financing products, eligibility requirements, collateral, personal guarantees, rates, fees, and repayment terms is based on company-provided statements and may vary depending on the specific product, applicant qualifications, and lending agreement. Business owners are encouraged to independently verify all information, carefully review financing agreements, and consult a qualified financial or legal professional before making borrowing decisions. Approval and funding are not guaranteed.